
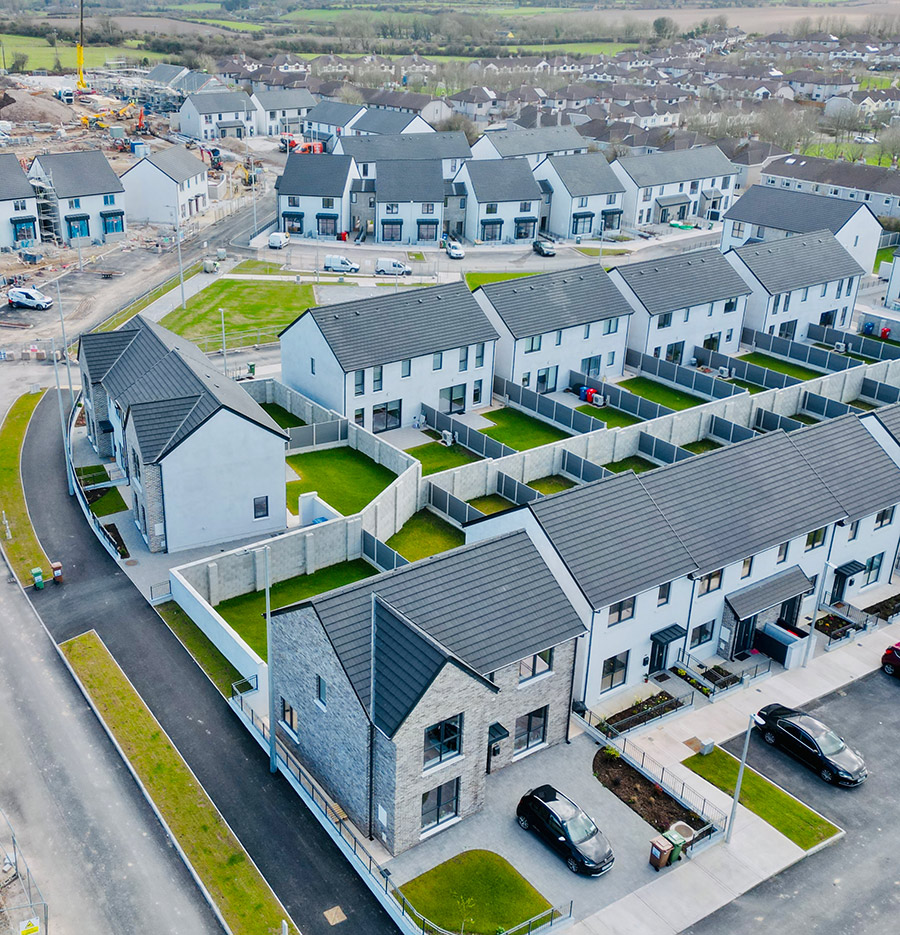
Property development can be highly rewarding, but it also requires careful financial planning. Whether you are building new homes, converting an existing property, refurbishing a commercial building or working on a mixed-use scheme, the right funding can make the difference between a project moving forward smoothly and a project becoming delayed.
Development finance is designed to help property developers fund construction, conversion and refurbishment projects. Unlike a standard mortgage, development finance is usually structured around the build programme, project costs, site value, expected end value and exit strategy.
For developers, understanding how development finance works is essential before purchasing a site or starting work.
What Is Development Finance?
Development finance is a type of short to medium-term funding used to support property development projects. It can help fund land purchase, construction costs, refurbishment work, professional fees and other project-related expenses.
This type of finance is commonly used for residential developments, commercial developments, mixed-use schemes, conversions and major refurbishment projects.
Rather than being based only on the current value of a property, development finance often considers the projected value of the completed scheme. This is known as the gross development value, or GDV.
How Development Finance Differs from a Standard Mortgage
A standard mortgage is usually arranged against a completed property that is ready for occupation or investment. Development finance is different because the property may not yet exist, may be partly built, or may require significant work before it reaches its final value.
Because of this, lenders look at different factors. They will usually assess the site, planning permission, build costs, developer experience, contractor details, expected sales value, project timeline and exit strategy.
The finance is often released in stages as the development progresses. This helps fund the work while allowing the lender to monitor the project.
What Can Development Finance Be Used For?
Development finance can be used for a wide range of property projects. This may include building new houses, constructing flats, converting offices into residential units, refurbishing commercial premises, developing mixed-use buildings or completing unfinished projects.
It may also be used to fund groundworks, materials, labour, professional fees and other costs directly linked to the development.
The exact use of funds will depend on the lender, the project and the structure of the finance agreement.
Residential Development Finance
Residential development finance is used for projects that create or improve homes. This may include new-build houses, apartment blocks, conversions, extensions, refurbishments and schemes where existing buildings are transformed into residential accommodation.
Lenders will usually want to understand the local housing market, expected sale prices, demand, planning status and build costs.
Residential development can offer strong potential, but the numbers need to be realistic. Overestimating sales values or underestimating costs can create problems later in the project.
Commercial Development Finance
Commercial development finance is used for projects involving business premises, such as offices, warehouses, industrial units, shops, hospitality venues or specialist commercial properties.
The lender may assess the likely demand for the completed property, whether it will be sold or let, and the strength of the local commercial market.
Commercial projects can be more complex because the end value may depend heavily on tenants, leases, location and the intended use of the property.
Mixed-Use Development Finance
Mixed-use development finance supports projects that include both residential and commercial elements. A common example is a building with retail or office space on the ground floor and flats above.
These projects can be attractive, but they may also require more detailed assessment. Lenders will want to understand each part of the development and how the final value will be achieved.
The exit strategy may involve selling residential units while retaining or letting the commercial space, so the funding structure needs to reflect the full plan.
How Funds Are Released
Development finance is usually released in stages. The first amount may help with the site purchase or refinance of an existing property. Further funds are then released throughout the project as work progresses.
These stage payments are often linked to valuations or monitoring reports. A lender-appointed surveyor may visit the site to confirm progress before the next drawdown is released.
This staged approach helps ensure that funds are used in line with the build programme and that the project remains on track.
Senior Debt in Development Finance
Senior debt is usually the main loan secured against the development project. It generally forms the largest part of the funding package and has priority over other types of borrowing.
Because senior debt is the first-ranking secured loan, it may offer a lower cost than more junior funding. However, lenders will still assess the project carefully before agreeing terms.
Senior debt may cover a percentage of the site value, build costs or gross development value, depending on the lender’s criteria.
Mezzanine Finance
Mezzanine finance can help bridge the gap between the senior debt available and the total funding required. It sits behind the senior lender and is often used when the developer wants to reduce the amount of cash they need to contribute.
Because mezzanine finance carries more risk for the lender, it is usually more expensive than senior debt.
It can be useful for experienced developers who have a strong project but need additional funding to complete the finance structure.
Bridging Finance for Development Sites
Bridging finance may be used before development finance is put in place. For example, a developer may need to secure a site quickly, complete a purchase at auction or refinance an existing property while planning permission is being finalised.
Once planning is granted or the project is ready to begin, the bridging loan may be replaced by development finance.
This can be a useful route where speed is important, but it should always have a clear exit plan.
The Importance of Planning Permission
Planning permission plays a major role in development finance. Many lenders will want planning consent in place before agreeing full development funding, especially for larger projects.
Some lenders may consider funding before planning is granted, but this can depend on the site, borrower experience and risk level.
Having clear planning approval, drawings, specifications and costings can strengthen an application and give lenders more confidence.
Gross Development Value Explained
Gross development value, often called GDV, is the estimated value of the project once it is complete. This figure is central to development finance because it helps lenders understand the potential end value of the scheme.
A professional valuation will usually be required to confirm the expected GDV. The lender will compare this with the purchase price, build costs, finance costs and developer profit.
If the figures do not leave enough margin, the lender may be cautious about funding the project.
Build Costs and Contingency
Accurate build costs are essential. Developers should prepare a detailed breakdown of construction costs, professional fees, materials, labour, utilities, insurance and any other project expenses.
It is also important to include a contingency fund. Development projects can face unexpected costs, delays or changes in material prices. A realistic contingency helps reduce the risk of running out of funds before completion.
Lenders will usually review the cost plan carefully before approving finance.
Developer Experience
Experience can make a significant difference when applying for development finance. Lenders often prefer borrowers who have successfully completed similar projects before.
This does not mean newer developers cannot access finance, but they may need stronger professional support, a lower-risk project or a more detailed plan.
If you are less experienced, working with a reputable contractor, architect, project manager and quantity surveyor may help strengthen the application.
Exit Strategies in Development Finance
An exit strategy is how the development finance will be repaid. Common exits include selling the completed units, refinancing onto a long-term mortgage, retaining the property as a rental investment or using another agreed funding route.
Lenders will want the exit strategy to be clear and realistic. If the plan is to sell, they will consider local demand and expected sale values. If the plan is to refinance, they will assess whether the completed property is likely to qualify for longer-term funding.
A weak or unclear exit strategy can make finance harder to secure.
Common Costs to Consider
Development finance can include several costs beyond the interest rate. These may include arrangement fees, valuation fees, legal fees, monitoring surveyor fees, exit fees, broker fees where applicable and professional costs.
Interest may be rolled up into the facility, meaning it is paid at the end, or serviced during the term, depending on the agreement.
Understanding all costs before starting is vital so the project remains profitable.
Risks Developers Should Be Aware Of
Property development carries risk. Build costs can increase, planning conditions can cause delays, contractors can fall behind, sales can take longer than expected and market values can change.
Development finance adds another layer of responsibility because the loan must be repaid within the agreed term.
A realistic budget, strong team, clear timeline and suitable finance structure can help reduce risk, but developers should always plan carefully before committing.
Preparing a Development Finance Application
A strong development finance application should include planning documents, drawings, costings, schedule of works, valuation details, site information, developer experience, contractor details, projected sales values and the exit strategy.
Lenders will want to understand the full project from start to finish. The clearer the information, the easier it is for them to assess the risk.
Good preparation can help avoid delays and improve the chance of finding a suitable funding option.
Why Professional Advice Matters
Development finance can be complex, and lender appetite varies depending on project type, location, loan size, experience and market conditions.
Professional advice can help developers compare funding options, understand lender requirements and structure the finance properly. This can be especially valuable for larger schemes, mixed-use projects, conversions, mezzanine funding or projects with tight timescales.
The right funding structure can support the development from purchase through to completion and exit.
Speak to Development Finance UK
If you are planning a residential, commercial or mixed-use development, Development Finance UK can help you explore suitable funding options. Whether you need senior debt, mezzanine finance, bridging finance or a tailored development funding structure, professional guidance can help you move forward with confidence.
Get in touch with Development Finance UK today to discuss your project and find a finance option that supports your development plans.
Development finance is subject to status, terms and conditions. Security will usually be required. Property or assets may be at risk if repayments are not maintained. Development projects carry risk, and independent legal, financial and tax advice should be sought where required.